FINANCIAL LESSONS
THE MONSOON TEACHES YOU!
Every year, the monsoon arrives without much warning. One afternoon the sky is fine, and by evening, half the city is flooded. Nobody who stepped out without an umbrella that morning planned to get soaked, they just didn't prepare.
Money works the same way. Financial shocks like a medical emergency, a job loss, a market downturn; rarely announce themselves in advance. The people who weather them best aren't those who are the luckiest. They're the ones who were already prepared before the first drop fell.
This Monsoon Fest, we thought we'd take the opportunity to show you ways in which you too can be prepared. Here are 10 financial lessons the rain has been quietly trying to show us all along.
1. EMERGENCY FUND = UMBRELLA FOR YOUR WEALTH
Just like you carry an umbrella before stepping out in the rain, you need a financial cushion in place before life surprises you. An emergency fund isn't exciting, it doesn't grow dramatically, it doesn't generate impressive returns, and most months you'll never touch it. But when you need it, nothing else will do.
The general guidance is to keep 6–12 months of essential living expenses in a liquid, accessible account. Your emergency fund should not be locked up in an investment, not sitting in a fixed deposit, and not mentally allocated for something else. This is your umbrella. It needs to be ready to open at a moment's notice.
Only once that cushion exists should you think about putting money to work through investments. Investing before you have an emergency fund isn't bold, it's like stepping out into the monsoon without anything to hold over your head and hoping it doesn't rain.
☔ Rain Check
Never invest money you may genuinely need in the next 6 months for family daily expenses, your parents' medical care, your children's school fees, or any other foreseeable need. Investment should come from your disposable income: money that, even in a worst-case scenario, won't disrupt you and your family's wellbeing.
2. REPAIR SMALL FINANCIAL LEAKS EARLY
A leaking roof doesn't fix itself. What starts as a small crack gets ignored through one monsoon season, then another, until the day the whole ceiling caves in and what would have been a minor repair becomes a complete rebuild.
Small financial problems work identically. A small debt left unpaid. A habit of lifestyle overspending that we think "isn't that much." A savings gap that keeps getting deferred to next month. These aren't problems that stay small. They compound in the financial sense and in the psychological one. The longer you leave them, the more entrenched they become, and the more they will cost you to fix.
The best time to repair a financial leak is the moment you spot it. Before the storm comes, not during it.
☔ Rain Check
A ৳500 monthly overspend ignored for 5 years is ৳30,000 quietly gone and that's before counting what it cost you in lost investment opportunity. Small leaks don't stay small. Prioritize closing your debts as soon as you can, and build the habit of reviewing where your money actually goes each month, not just where you intend it to go.
3. RICH ON PAPER, BROKE IN THE RAIN
Cash flow matters more than most people realize, until they need it and don't have it. Bangladesh's dominant investment culture centers around land and gold, both of which are real stores of value. But they share one critical weakness: you cannot spend them quickly when you need to.
Real financial security isn't only about how much you own. It's about how much of what you own can move when you need it to. A family with a plot in Purbachal and ৳5,00,000 in savings is better prepared for a sudden medical emergency than one with three plots and no liquid funds at all. Wealth that can't reach you in a crisis isn't protection, it's like a show-piece.
This doesn't mean land and gold have no place in a financial plan. It means they shouldn't be all of your financial plan. Liquidity isn't glamorous. But it's what actually keeps you standing when the storm hits.
☔ Rain Check
Owning a plot in Purbachal doesn't help you if a medical emergency hits tonight. You can't sell it within hours, and even if you could, registration fees alone would eat a significant portion of it. Always maintain some portion of your wealth in a form you can actually access when the rain starts.
4. ONE FLOODED ROAD, MANY ROUTES
When one road gets flooded in Dhaka, the seasoned commuter doesn't sit and wait for it to clear. They know three alternate routes and take the best one available. The person who only knows one road home has no options.
Your investment portfolio works exactly the same way. Concentrating everything in a single asset, a single business, or a single type of investment leaves you with no detour when that one road floods. Diversifying your investment by spreading across multiple campaigns, multiple sectors, and multiple asset types means that when one investment underperforms, your entire financial plan doesn't stall with it.
This applies within halal investing too. Spreading across different campaigns on biniyog.io with different risk grades, different industries, and different tenures is genuine diversification. And ideally, your portfolio also extends beyond any single platform, across other halal-compatible asset classes as well.
☔ Rain Check
Investing all your capital in a single campaign or in multiple campaigns from the same business concentrates your risk entirely in one place. If that business faces difficulties, so does all of your invested money. Spread across multiple businesses of various risk grades, and also plan to diversify across different halal asset classes over time.
5. THE INVESTOR PROTECTION POOL = YOUR FINANCIAL RAINCOAT
You don't feel the value of a raincoat until you're caught in a downpour. On a clear day, it seems unnecessary. During a downpour, it's everything. Financial protection works the same way, it feels like an expense you don't need right up until the moment you do.
biniyog.io's Investor Protection Pool is built on a Takaful-based model: a community safety net where a portion of every investment goes into a shared pool. If a campaign repayment is delayed for more than six months, the pool steps in to help cushion the impact for investors. It doesn't eliminate risk, nothing genuinely does, but it means you're not completely exposed if one campaign faces difficulty.
Think of it as the last layer of your financial raincoat, not the first. Your primary protection is your own careful diversification and due diligence. The pool is the layer underneath, for the storms that get through everything else.
☔ Rain Check
The Protection Pool doesn't eliminate risk, no raincoat stops every drop. It reduces the impact of a bad outcome, not the probability of one. Treat it as your final layer of cover, not your only one. If you invest regularly through biniyog.io, explore joining the Protection Pool today:
biniyog.io/investor-protection-pool
6. DON'T PANIC WHEN THE MARKET GETS CLOUDY
Every monsoon brings Kalboishakhi, where we suddenly get non-stop rain, flooding streets and power outages. And then, without announcement, it passes. The sun returns. The city moves on.
Economic storms follow the same pattern. Market downturns, currency volatility, geopolitical shocks, rising inflation - all these are real, they cause real pressure, but they pass. The investors who emerge from them with their wealth intact are not the ones who were the most reactive. They are the ones who stayed patient, stayed diversified, and resisted the urge to make permanent financial decisions in response to temporary weather.
Panic is one of the most expensive financial behaviors there is. The instinct to "do something" when things look bad very often leads to locking in losses that would have recovered, or abandoning a strategy that was fundamentally sound. Patience is the most underrated financial strategy.
☔ Rain Check
Withdrawing or abandoning investments the moment things look uncertain is like throwing away your umbrella because it started raining. That is exactly when it is most valuable. Rain passes. Stay covered without panicking.
7. YOUR MONEY SHOULD WORK, NOT JUST GET WET
Leaving money idle in a current account or savings account feels safe. The number doesn't go down. Nothing alarming happens. But quietly, steadily, inflation is doing what the rain does to an unprotected surface, eroding it.
This is one of the most important and least-discussed financial realities in Bangladesh. When your savings account returns 6% and inflation is running at 10%, you are not earning 6%. You are losing approximately 4% in real purchasing power every year. The number you see as your bank balance grows steadily but the amount of valuable things you can actually purchase with that number shrinks over time.
Money that genuinely works after being invested in real, Shariah-compliant businesses and generates actual revenue, has the opportunity to grow faster than inflation. It's not guaranteed, and it carries risk. But it is a fundamentally more honest relationship with money than the false comfort of a savings account in an inflationary environment.
☔ Rain Check
Bangladesh's inflation ran above 10% in 2024. A savings account returning 6% in that environment didn't protect your money, it just slowed down how quickly it lost value. Idle money isn't safe. It's just losing value quietly.
8. UMBRELLAS AREN'T JUST FOR THE RICH AND NEITHER IS INVESTING
Nobody gets a pass on the monsoon. Rich or not, old or young, the rain falls on everyone equally. And so everyone carries an umbrella because the alternative is getting soaked.
Investing has long carried the cultural perception in Bangladesh that it's something you do once you're already comfortable, once you've saved up a significant amount, once the family obligations are settled, once life is a little more stable. But that delay turns extremely expensive when we consider compounding growth.
Moreover, In our nation it isn’t just our mindset that acts as a barrier, the structural barrier is also a genuine problem. The minimum investment amounts for most formal instruments are inaccessible for average earners. That’s what we aimed to change by giving the option to start investing from just ৳5,000 at our platform. Through biniyog.io, you can invest in a real, verified, Shariah-compliant business all from the comfort of your home. You don't need lakhs to start protecting your financial future. You just need to start.
☔ Rain Check
Starting with ৳5,000 in an investment campaign is better than waiting until you have ৳50,000 and doing nothing in the meantime. The monsoon doesn't wait for you to feel ready. Neither does compound growth.
9. KNOW THE RISKS BEFORE YOU STEP OUTSIDE
Before you leave the house on a monsoon morning, you check the weather. Not because you're afraid of rain but because knowing what's coming lets you prepare appropriately. Light drizzle gets a light jacket. Heavy downpour gets the good umbrella and the waterproof bag.
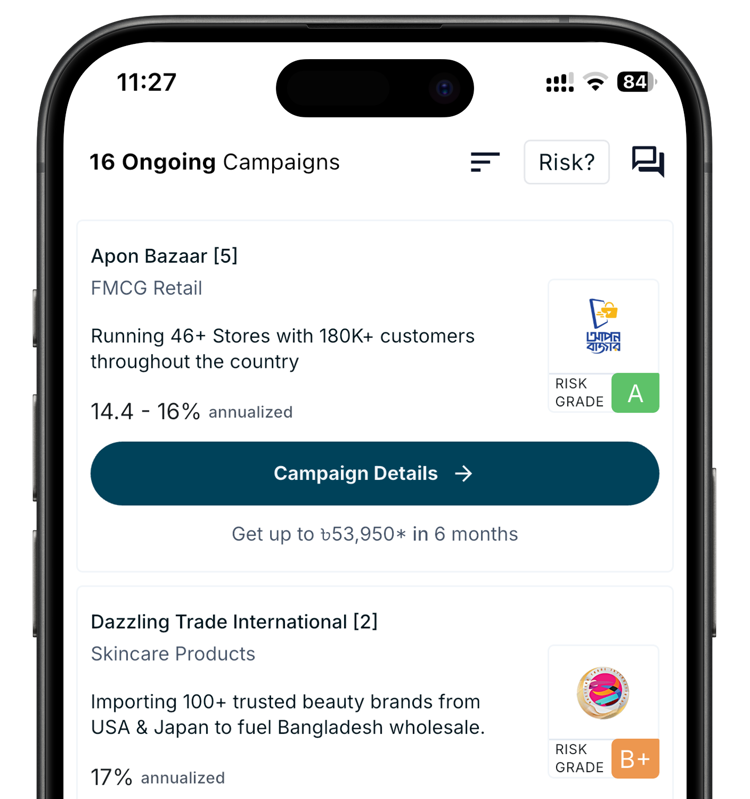
The same logic applies to every investment decision you make. Before committing money to any campaign, read the contract details, understand how the financing is structured, and check the risk grade. On biniyog.io, every campaign is presented with transparent information in the campaign details section: the business type, the financing structure, the tenure, and the risk grade. They are all given so that you can make this call with clear information rather than guesswork.
No investment is entirely risk-free. Not on biniyog.io, not anywhere. Real businesses operate in a real world subject to real market forces. The goal isn't to avoid all risk, it's to understand the risk you're taking and decide whether it fits your situation.
☔ Rain Check
Risk Grade A is a light drizzle and it’s manageable with basic preparation. Risk Grade B is heavier rain which is still manageable, but both teach us to bring a good umbrella. Both are real risks, and both require knowing what you're stepping into.
To understand risks and investment reality on biniyog.io in more depth, read:
biniyog.io/understanding-risks-101
10. WHATEVER THE FORECAST, RAIN CAN FALL ANYWHERE, ANYTIME
The monsoon doesn't always send a warning. Sometimes the morning is perfectly clear and by afternoon the streets are flooded. The weather forecast is a guide, not a guarantee.
Financial risk is exactly the same. You can read the market carefully, choose verified businesses, diversify thoughtfully, and still encounter something unexpected like a global economic shock, a sudden policy change, a sector-wide disruption, etc. This isn't a reason to avoid investing. It's a reason to invest prepared.
Prepared doesn't mean fearful. It means you have your emergency fund in place, your investments are diversified, you understand the risks of what you've chosen, your investment money is money you can genuinely set aside, and you have the patience to stay the course when temporary weather makes things look uncertain.
That combination of knowledge, diversification, liquidity and patience is your financial umbrella. Keep it open before the first drop falls, not after.
☔ Rain Check
Being prepared for risk is not the same as being afraid of it. Prepared investors don't panic in the storm because they already came equipped for it. The rain will come, it always does. The only question is whether your umbrella is already open when it does.
FINAL THOUGHTS
The monsoon can be inconvenient but it also teaches us a truth that applies to money as much as it applies to commuting: the people who prepared before it rained are the ones who are fine. Everyone else is struggling.
Build your emergency fund. Repair the small leaks before they become big ones. Keep some liquidity alongside your assets. Diversify. Don't panic when the market clouds over. Put your idle money to work. Start now with whatever you have. Understand what you're investing in. And stay prepared for the storms that arrive without warning.
The rain doesn't wait. Neither should your financial preparation.
For any questions, leave us a message or contact our support.
Your financial well-being is our topmost priority & our team is always here to help. Visit biniyog.io or reach out to our support team.
DOWNLOAD OUR APP
Start your journey to wealth.
Our halal investments are structured in accordance with the strictest Islamic principles.


Office Level 5, House 60, Kazi Nazrul Islam Avenue, Dhaka 1215
Contact +880 1886 064 046


